Last updated: October 2026 · Reading time: 13 minutes Imagine you bought two bitcoin in 2021 at €60.000 each, totalling €120.000. On 31 December 2025, the snapshot date (fotomoment) of the new capital…
Last updated: October 2026 · Reading time: 13 minutes
Imagine you bought two bitcoin in 2021 at €60.000 each, totalling €120.000. On 31 December 2025, the snapshot date (fotomoment) of the new capital gains tax, BTC stands at €38.000. Your portfolio is then worth €76.000 on paper, while you paid €120.000. That difference of €44.000 is an unrealised loss. Not yet realised, but painful in your calculation model.
The Act of 6 April 2026 provides an exception for this situation. Under strict conditions, at the time of disposal you may choose your actual purchase value as the basis, instead of the value on 31/12/2025. That reduces your taxable capital gain, but only if you sell before 31 December 2030. After that the option disappears.
This guide explains exactly how the offset window works, what the statutory anchor is, and illustrates with three worked examples what a typical crypto investor gains from it.
What is an unrealised loss exactly?
The Belgian capital gains tax (meerwaardebelasting) has applied a step-up cost basis for crypto held before 2026 since 1 January 2026: the market value on 31 December 2025 (the so-called snapshot date / fotomoment) becomes your default cost price. As a result, only the capital gain after that date is taxed at 10%.
But what if your actual purchase price is higher than that snapshot value? Then there is an unrealised loss in your position: the amount of your paper loss at the snapshot date, namely (purchase price minus snapshot value) x quantity.
It is a latent (unrealised) loss because it only becomes visible at the moment of realisation (disposal, swap, payment). Until then it exists only on paper.
Statutory anchor: Art. 102 §4 WIB 92
The exception is set out in Article 102 §4 WIB 92, introduced by the Act of 6 April 2026 on the introduction of a tax on capital gains on financial assets (published in the Belgian Official Gazette on 21 April 2026). The relevant passage:
"In that case, by way of derogation from paragraph 1, fourth indent, the capital gain is calculated on the basis of the average purchase value per financial asset held by the taxpayer or their predecessor before 31 December 2025."
In plain terms: at the taxpayer's request ("op verzoek van de belastingplichtige") the average actual purchase value may be used instead of the average snapshot value, per financial asset. It is not an automatic offset; it is a per-asset election that you make explicitly.
The 5-year deadline: 31 December 2030
The legislature has limited the election in time. Art. 102 §4, last sentence provides that the election is only available for disposals on or before 31 December 2030. From 1 January 2031 the exception lapses and the snapshot value on 31/12/2025 is mandatory for whatever remains of your pre-2026 holdings.
In summary:
| Disposal date | Which basis | Election possible? |
|---|---|---|
| before 1 January 2026 | old regime (no capital gains tax on normal management) | n/a |
| 2026 through 2030 | snapshot 31/12/2025 (default) or actual purchase value (election) | yes, per-asset |
| from 1 January 2031 | snapshot 31/12/2025 mandatory | no |
The five years were not chosen innocently: the statutory anchor is the standard investigation period of the tax authority. The legislature aligned the election period with the period during which the taxpayer still bears the burden of proof for the original purchase.
How to calculate the election (per-asset weighted-average)
Two things to keep straight: it is per asset (per token, not per lot), and it is weighted-average (average purchase value, not FIFO).
Concretely, for one asset:
- Sum the purchase prices of all pre-2026 lots you still held on 31/12/2025 (in EUR, excluding sales between purchase and snapshot date)
- Divide by the pre-2026 quantity you held on 31/12/2025
- Result = your elected wavg for that asset
- On disposal in 2026 through 2030: capital gain = sale price - (elected wavg x quantity sold)
Without the election the ordinary rule of Art. 102 §1, fourth paragraph WIB 92 applies: FIFO, what you bought first is deemed to be sold first. Your pre-2026 holdings then carry a single price, the value on 31/12/2025, and are sold as the first block. Within that block the order makes no difference. The weighted average of your actual purchase prices only applies when you activate the §4 election: the gain is then calculated, "by way of derogation from" that FIFO rule, on the average purchase value "per financial asset".
Important: no deductible loss from the election
The law contains an important no-loss guard. Art. 102 §4, fourth indent refers to "the positive difference": the election can reduce a capital gain, but cannot create a deductible loss. In practice that gives three cases:
- Sale price above your elected wavg: the gain is calculated on your actual average purchase value.
- Sale price between the value on 31/12/2025 and your elected wavg: the gain becomes zero. You pay nothing, but you do not get a deductible loss either.
- Sale price below the value on 31/12/2025: the election does not apply. Your loss is measured against the value on 31/12/2025, just as without the election.
The rationale: pre-2026 paper losses must not appear as new fiscal losses through the election. The legislature only intended to allow post-2026 gains to be calculated more accurately, not for old losses to become deductible for the first time.
Three worked examples
The prices in the introduction and in these examples are fictitious and chosen to keep the arithmetic simple. The screenshots further down show the actual values on 31/12/2025.
Example 1: small unrealised loss, disposal in 2027
Robin bought 1 BTC in March 2021 at €50.000. On 31/12/2025 BTC stands at €38.000. Unrealised loss = (50.000 - 38.000) = €12.000. In June 2027 Robin sells the BTC for €60.000.
| Method | Basis | Sale | Capital gain | Tax (10%) |
|---|---|---|---|---|
| Default (snapshot) | 38.000 EUR | 60.000 EUR | 22.000 EUR | 2.200 EUR |
| Election (actual purchase) | 50.000 EUR | 60.000 EUR | 10.000 EUR | 1.000 EUR |
Benefit of the election: €1.200 less tax. Robin must request this per asset and keep the purchase invoice (Bitvavo export from 2021) as proof.
Example 2: multiple lots, partial disposal in 2029
Iman bought ETH in four tranches during 2021 and 2022. On 31/12/2025 he holds 10 ETH.
| Purchase date | Quantity | Purchase price/ETH | Total |
|---|---|---|---|
| Jan 2021 | 3 ETH | 1.500 EUR | 4.500 EUR |
| May 2021 | 2 ETH | 3.200 EUR | 6.400 EUR |
| Nov 2021 | 2 ETH | 4.000 EUR | 8.000 EUR |
| Jul 2022 | 3 ETH | 1.800 EUR | 5.400 EUR |
| Total pre-2026 | 10 ETH | - | 24.300 EUR |
Elected wavg = 24.300 / 10 = 2.430 EUR per ETH.
On 31/12/2025 ETH stands at 2.000 EUR, so snapshot wavg = 2.000 EUR per ETH. The unrealised loss is 430 EUR per ETH, or 4.300 EUR for the full position.
In March 2029 Iman sells 6 ETH for 3.500 EUR each (total 21.000 EUR).
| Method | Basis (6 ETH) | Proceeds | Capital gain | Tax (10%) |
|---|---|---|---|---|
| Default (snapshot) | 12.000 EUR | 21.000 EUR | 9.000 EUR | 900 EUR |
| Election (actual purchase) | 14.580 EUR | 21.000 EUR | 6.420 EUR | 642 EUR |
Benefit: 258 EUR. For the remaining 4 ETH the election is preserved as long as Iman sells them before 1 January 2031. Cumulatively across the full pre-2026 holdings the difference amounts to 430 EUR per realised ETH.
Note the statutory €10.000 annual exemption: the ultimately taxable capital gain is further reduced by that exemption on your total crypto result.
Example 3: disposal in 2031, election expired
Sara bought 2 SOL in 2022 at 150 EUR each. On 31/12/2025 SOL stands at 100 EUR. She sells in February 2031 at 350 EUR each.
| Method | Available? | Basis | Capital gain |
|---|---|---|---|
| Default (snapshot) | mandatory after 2030 | 200 EUR | 500 EUR |
| Election (actual purchase) | expired on 31/12/2030 | n/a | n/a |
The 100 EUR unrealised loss Sara could have offset (50 EUR per SOL x 2) is permanently lost due to the delayed disposal. This illustrates the importance of the 5-year offset window: anyone holding crypto that was below their purchase price on 31/12/2025 would do well to plan a disposal strategy well before the deadline of 31 December 2030.
Tax-on-web mechanics
The capital gains tax on crypto is declared in Box XIII (Vak XIII - Diverse inkomsten / Miscellaneous income) of Tax-on-web. The net capital gain, after applying the annual exemption and any elections, is entered under the specific crypto section that FOD Financiën (the Belgian tax authority) activates from declaration year 2027 (income year 2026).
For the election itself there is no separate code. You enter the net taxable amount after election and keep the underlying calculation ready as proof (purchase invoices, snapshot-date valuation, wavg calculation per asset). The tax authority can audit up to 7 years back to check whether the election was correctly applied.
Practical tip: document the election in an Excel overview or via your crypto tool, and keep a PDF snapshot of your portfolio as at 31/12/2025 (the step-up basis). See also our guide on the step-up rule for crypto.
How to activate the election in Cryptotax
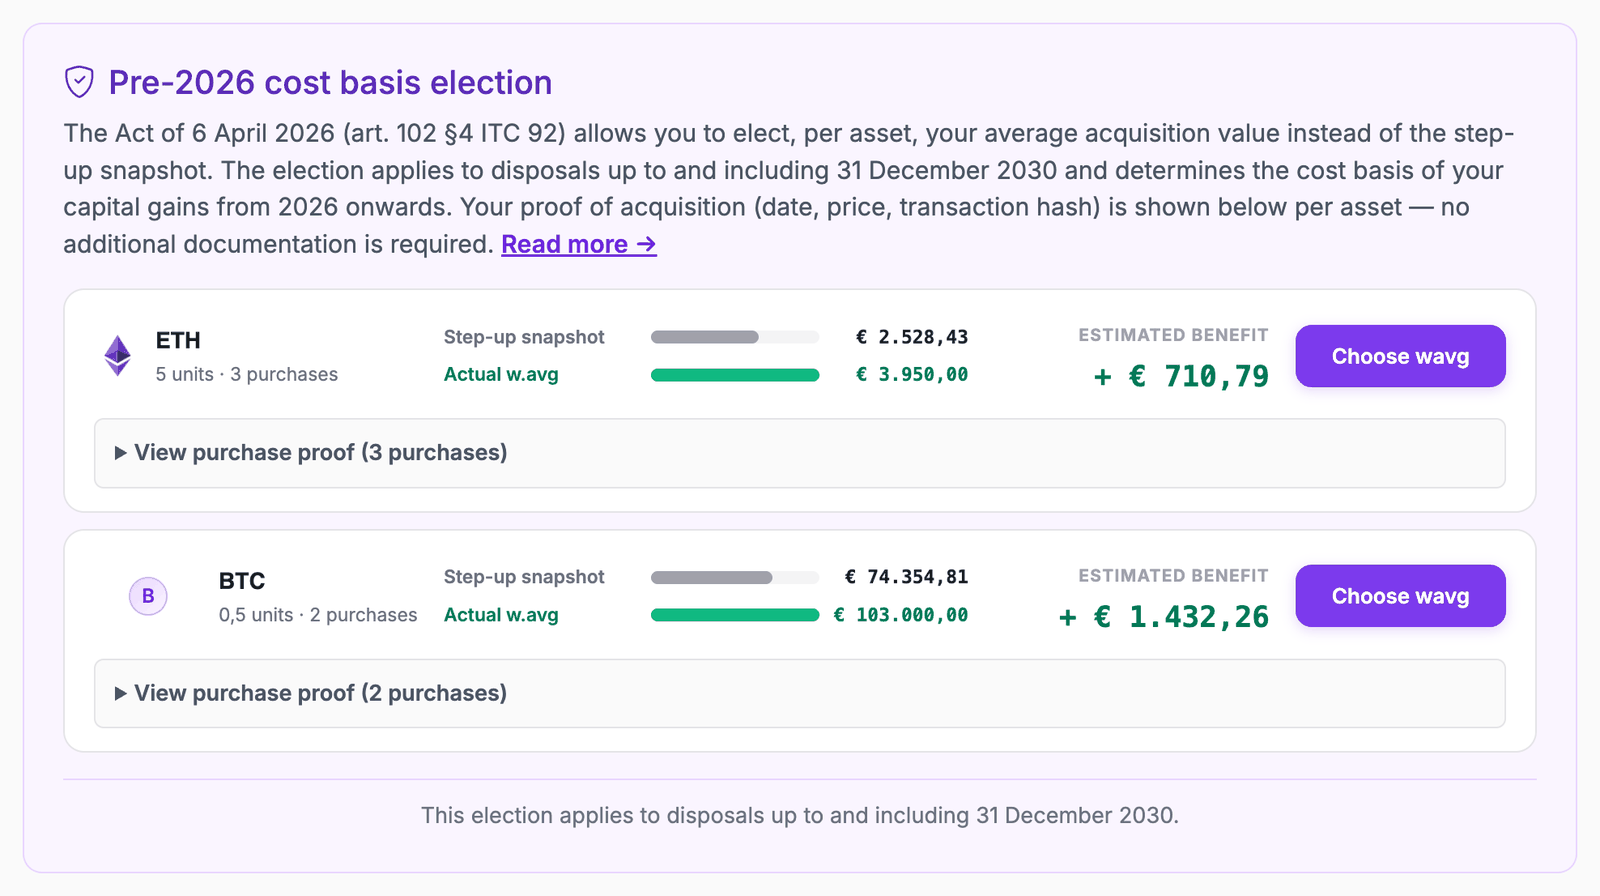
For every asset you held on 31/12/2025, Cryptotax calculates two figures: the value on the snapshot date (the default cost basis) and the weighted average of your actual purchase prices. If that average is higher, your position carries an unrealised loss and the election can lower your tax.
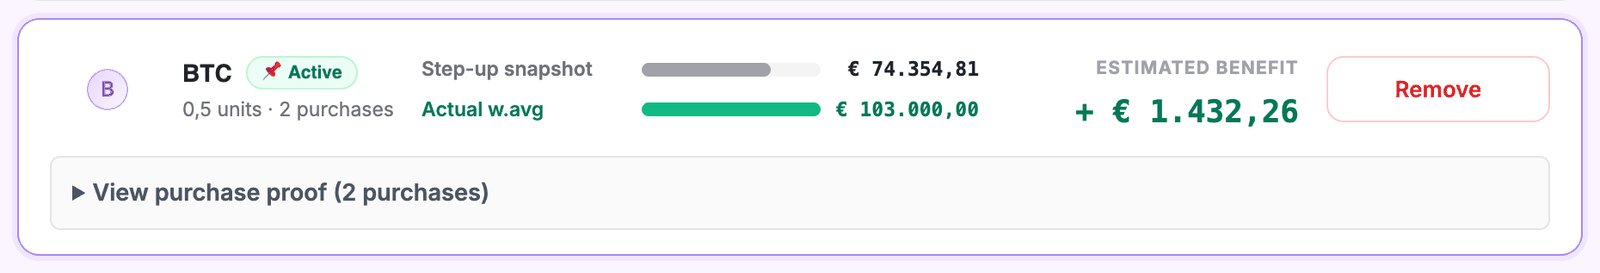
The screenshots below come from an example account with a Bitvavo export: 5 ETH bought between 2021 and 2025 at an average of €3.950, and 0,5 BTC bought in late 2024 and October 2025 at an average of €103.000. In January 2026, 0,2 BTC was sold at €82.000.
Step 1: open the card on your 2026 dashboard
If at least one asset carries an unrealised loss, your 2026 tax year overview shows the card Pre-2026 cost basis decision. It shows how many assets qualify and the estimated total benefit. Click View & choose.
Step 2: compare the two cost bases per asset
For each asset you see the step-up snapshot (the value on 31/12/2025) next to your actual w.avg (the average purchase price of what you held at that time). Only assets whose actual w.avg is higher appear in this list. Assets that were in profit on the snapshot date do not show up: for them the snapshot is already the most favourable basis.
The estimated benefit is 10% of your full unrealised loss: (actual w.avg minus snapshot) × quantity × 10%. For the 0,5 BTC that is (103.000 − 74.354,81) × 0,5 × 10% = €1.432,26. That is an upper bound. What you actually save depends on when and at what price you sell (see step 4).
Step 3: check your purchase proof
Under each asset, expand View purchase proof. You see every purchase that counts towards the average, with date, quantity, price, total, source and reference. This is the evidence you need to be able to show if the tax authority asks how you arrived at your purchase value. Compare it with your exchange export before you make the election.
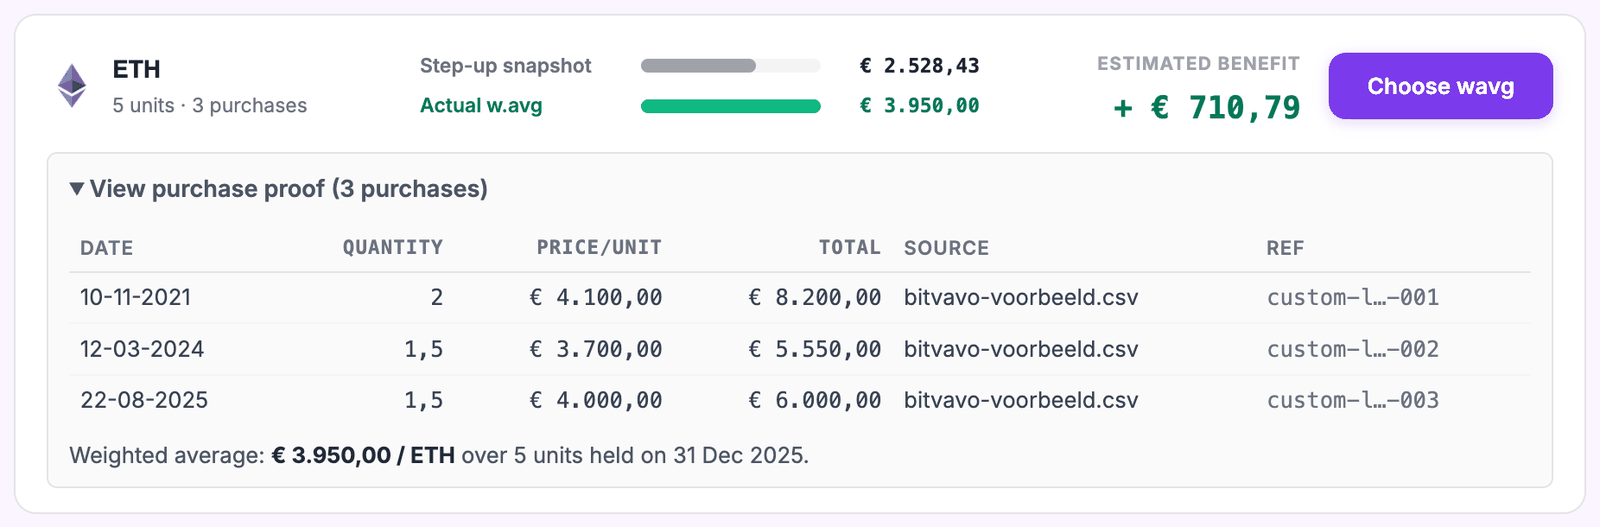
Step 4: choose wavg and check the effect
Click Choose wavg next to the asset you want to elect. Cryptotax saves your election and immediately recalculates your taxes. The asset then gets the label Active. Remove puts the asset back on the step-up snapshot.
You see the effect on your 2026 dashboard. In the example, 0,2 BTC was sold at €82.000. Without the election the basis is the value on 31/12/2025 (€74.354,81), giving a capital gain of €1.529,04. With the election the basis is your average purchase price of €103.000. Because the sale price lies between the snapshot and that average, the gain drops to zero instead of turning into a loss: the no-loss guard described above.
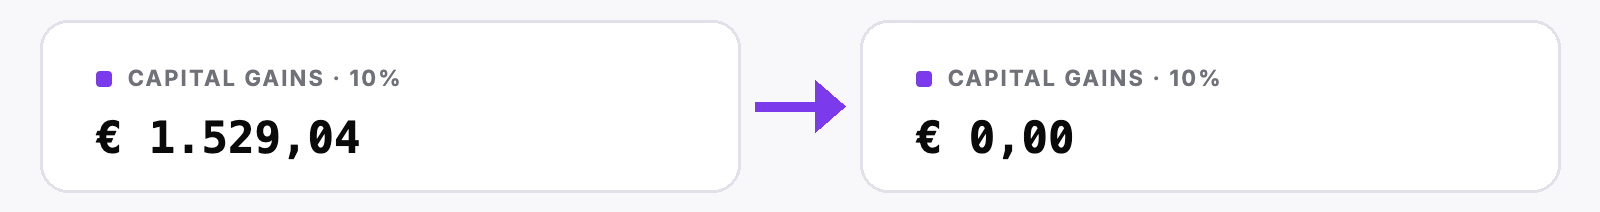
The election applies per asset and to disposals up to and including 31 December 2030. If you sell later, Cryptotax automatically uses the value on 31/12/2025.
Start a free scan to see for your own portfolio which assets qualify and what the election is worth.
Frequently asked questions
Can I carry my unrealised loss forward to future years?
No. The election offsets within the calculation of a capital gain on a disposal. No separate fiscal loss arises that can be carried forward. Concretely: you use your unrealised loss only at the moment you sell the asset concerned, and only up to and including 31 December 2030.
What if I sell after 2030?
Then the election lapses and the snapshot value of 31/12/2025 is your mandatory basis. The unrealised loss you could have used is permanently lost from a tax perspective. Anyone holding crypto that was below the purchase price on 31/12/2025 would do well to set up a timely disposal plan.
Does the election also apply to stablecoins and EUR-pegged tokens?
Yes, stablecoins are financial assets within the meaning of the law. In practice the difference between snapshot value and purchase value will be limited (typically a few euro-cents per token), so the fiscal impact is negligible. Requesting the election for a stablecoin position is administratively possible but rarely worth the effort.
What if some of my lots show a gain and others a loss (mixed unrealised gains and losses)?
The election is per-asset, not per-lot. You calculate one average purchase value for your full pre-2026 position in that asset. You compare that single wavg figure with the snapshot value. If the wavg is higher than the snapshot there is a net unrealised loss and the election may be beneficial. If the wavg is lower (net unrealised gain), the election is disadvantageous and you choose the snapshot basis.
What about DCA purchases (dollar-cost averaging) over multiple years?
DCA does not change the mechanics: you add up all pre-2026 purchase prices, divide by the pre-2026 quantity, and you have your elected wavg. Do bear in mind the burden of proof: for each DCA tranche you must be able to produce a purchase record (exchange export, bank statement for P2P, transaction hash for on-chain purchase).
Summary
- Unrealised loss = purchase price minus snapshot value on 31/12/2025, unrealised at the snapshot date
- Under Art. 102 §4 WIB 92 you may elect per asset to use the average actual purchase price as the basis instead of the snapshot value
- This election is only available for disposals on or before 31 December 2030
- Per asset, weighted-average by way of derogation from the ordinary FIFO rule (no per-lot choice)
- No deductible loss from the election: if you sell between the value on 31/12/2025 and your elected wavg, your gain becomes zero; if you sell below the value on 31/12/2025, the ordinary snapshot basis applies
- Burden of proof on the taxpayer: keep purchase invoices and wavg calculation per asset
- In Cryptotax you compare both cost bases per asset and activate the election in one click via Pre-2026 cost basis decision
Calculate for your portfolio whether the unrealised-loss election still applies and which disposal strategy offers the most fiscal benefit.
Read also: capital gains tax on crypto, the step-up rule, declaring crypto losses, offsetting capital losses and opt-in / opt-out of the capital gains tax.
Sources:
- Act of 6 April 2026 introducing a tax on capital gains on financial assets (Belgian Official Gazette, 21 April 2026)
- Income Tax Code 1992 (WIB 92), Art. 90 and 102
- Belgian Official Gazette, 21 April 2026 (publication of the Act of 6 April 2026)
Disclaimer: This article is purely informational and does not constitute individual tax advice. Applying the unrealised-loss exception requires a correct wavg calculation per asset, a disposal plan within the 5-year window, and proper supporting documents. Consult a recognised Belgian tax adviser for specific cases, or request a ruling from the Dienst Voorafgaande Beslissingen.